Institutional Risk Intelligence  ·  Singapore

Vol is a price.
Fragility is a state.

When markets rebound, what evidence do you use to decide whether to restore risk?

We peer beneath the index to read the constituent surface and measure how it reacts to price shocks daily. A similar index reading can sit on top of completely different market structures that impact exposure and hedging costs.

Fragility Score

90th

percentile, against its own history

HIGH

US large-cap equities · Market session · 21 Oct 2026

Recent daily history · 63 sessionsPercentile · 0–100 · missing observations are not joined
05010024 Jul 20268 Sept 202621 Oct 2026
View dated readings
Fragility readings, most recent first
SessionPercentile
2026-10-2190.08
2026-10-2092.46
2026-10-1993.39
2026-10-1691.01
2026-10-1550.79
2026-10-1452.65
2026-10-1334.13
2026-10-1234.79
2026-10-0934.39
2026-10-0830.56
2026-10-0728.04
2026-10-0630.16
2026-10-0530.16
2026-10-0229.89
2026-10-0128.84
2026-09-3029.23
2026-09-2930.16
2026-09-2830.16
2026-09-2520.11
2026-09-2420.11
2026-09-2319.44
2026-09-2220.77
2026-09-2120.37
2026-09-1818.52
2026-09-1720.24
2026-09-1621.69
2026-09-1515.61
2026-09-1419.58
2026-09-1118.12
2026-09-1011.77
2026-09-0911.51
2026-09-0811.64
2026-09-0426.19
2026-09-0327.78
2026-09-0226.46
2026-09-0125.13
2026-08-3118.78
2026-08-2818.25
2026-08-2719.18
2026-08-2618.92
2026-08-2518.92
2026-08-2418.92
2026-08-2117.20
2026-08-2017.46
2026-08-1914.95
2026-08-1814.15
2026-08-1710.05
2026-08-146.61
2026-08-139.26
2026-08-1210.19
2026-08-1110.05
2026-08-107.01
2026-08-076.61
2026-08-066.48
2026-08-056.35
2026-08-0410.05
2026-08-0313.49
2026-07-3116.80
2026-07-3016.40
2026-07-2911.90
2026-07-2840.74
2026-07-2739.68
2026-07-2439.68

Source: Altus production · last updated 22 Oct 2026 · history reflects the current research vintage and may be restated.

Who it is for

Two desks.
One surface.

The same reading answers a different question on each desk. Start with yours.

01

Volatility

Every calm costs the same carry, and on VIX every calm looks alike.

  • Whether the names have stopped repricing, or protection beneath the index is still being re-marked
  • What a fall does to the strike you hold: at the surface, at the held strike and at the bid
  • How the correlation trade’s response to falls has changed since 2023

ReadMore tilt, less levelIndex puts at the bidCorrelation on falls

02

Equity long/short

Revisit gross exposure, or deal with a handful of positions?

  • Whether unusual repricing is concentrated in your holdings or shared across the market
  • Whether a rebound has reversed the downside repricing beneath the index, or it persists
  • Evidence for the discussion about restoring risk, not a prompt to take it

ReadIn 2025 the index recovered. The surface beneath it had not.Terrain and fragility

Family offices, and equity allocation and overlay teams at pensions and insurers, read the same two layers with the equity desk’s questions: whether the planned rebalance still makes sense, and whether the protection still fits the budget.

Research

What we are writing.

All research
IV STRESS →SYNCHRONISATION OF IV MOVEMENT →LS · Localised stressElevated IV stress · lower synchronisationStress sits in a few names17% of sessions · median spell 8 sessionsSS · Synchronised stressElevated IV stress · higher synchronisationStress is broad and collective35% of sessions · median spell 18 sessionsCD · Calm and dispersedSubdued IV stress · lower synchronisationNames reprice on their own34% of sessions · median spell 19 sessionsSC · Synchronised calmSubdued IV stress · higher synchronisationStress has left prices, not co-movement13% of sessions · median spell 8 sessions7 of 317 of 315 of 329 of 2924 of 3223 of 3124 of 3120 of 29
Framework · All

Terrain and fragility: two readings beneath the index

Two questions define the terrain: how strongly is constituent implied volatility priced, and how collectively are names repricing? A third asks how the surface responds to index moves. Each reading is ranked against its own history, so a session can be set beside any earlier one.

Read 8 min
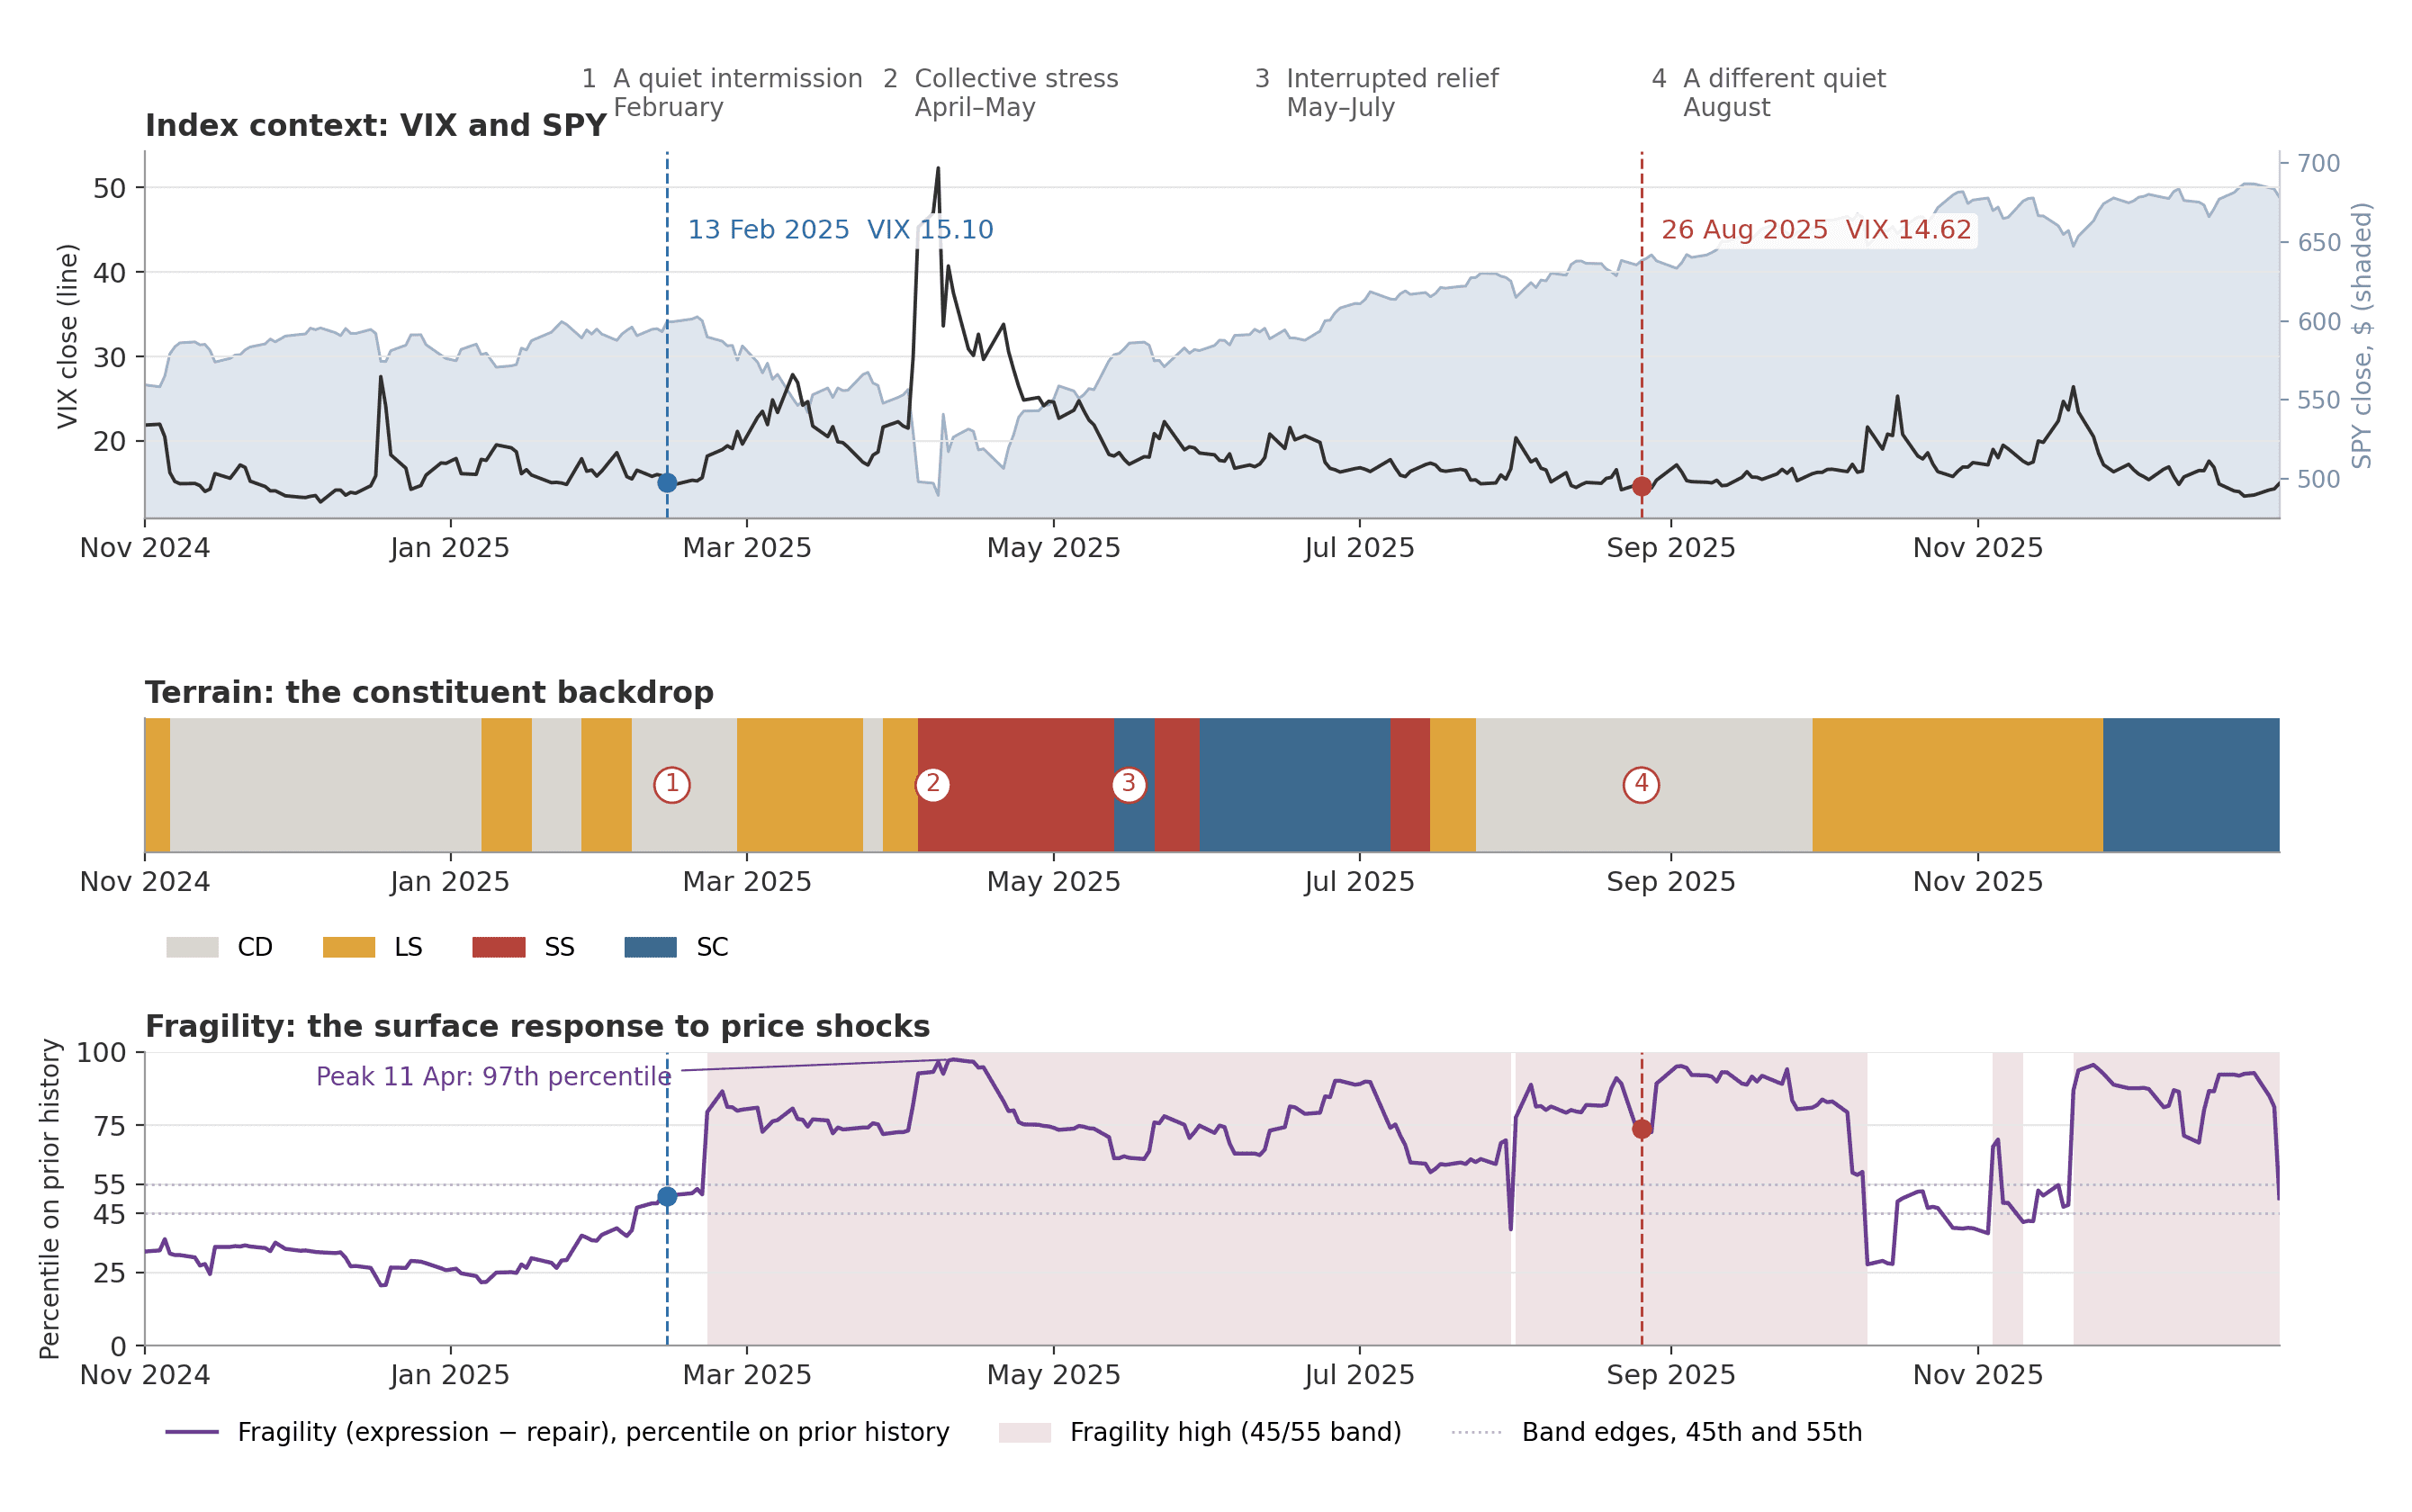
VIX close with SPY's adjusted close shaded behind it (upper panel), the terrain cell by session (middle), and the fragility percentile on its own prior history (lower), November 2024 to December 2025, read at each close. Shading marks sessions on which fragility read High under the 45/55 band, whose edges are dotted. The two dates, 13 February and 26 August 2025, are marked.
Study · All

In 2025 the index recovered. The surface beneath it had not. Eleven years say the same.

On 13 February and 26 August 2025 VIX and COR1M read almost the same, yet beneath the index fragility had moved from Low to High and 29 of 44 names showed lower co-movement. Over 2,766 sessions the two layers separate easing stress from fuller recovery: the road into an event ran along the high-fragility deck and relief took two routes. A closing section asks what this leaves for a book hedged with the index.

Read 12 min
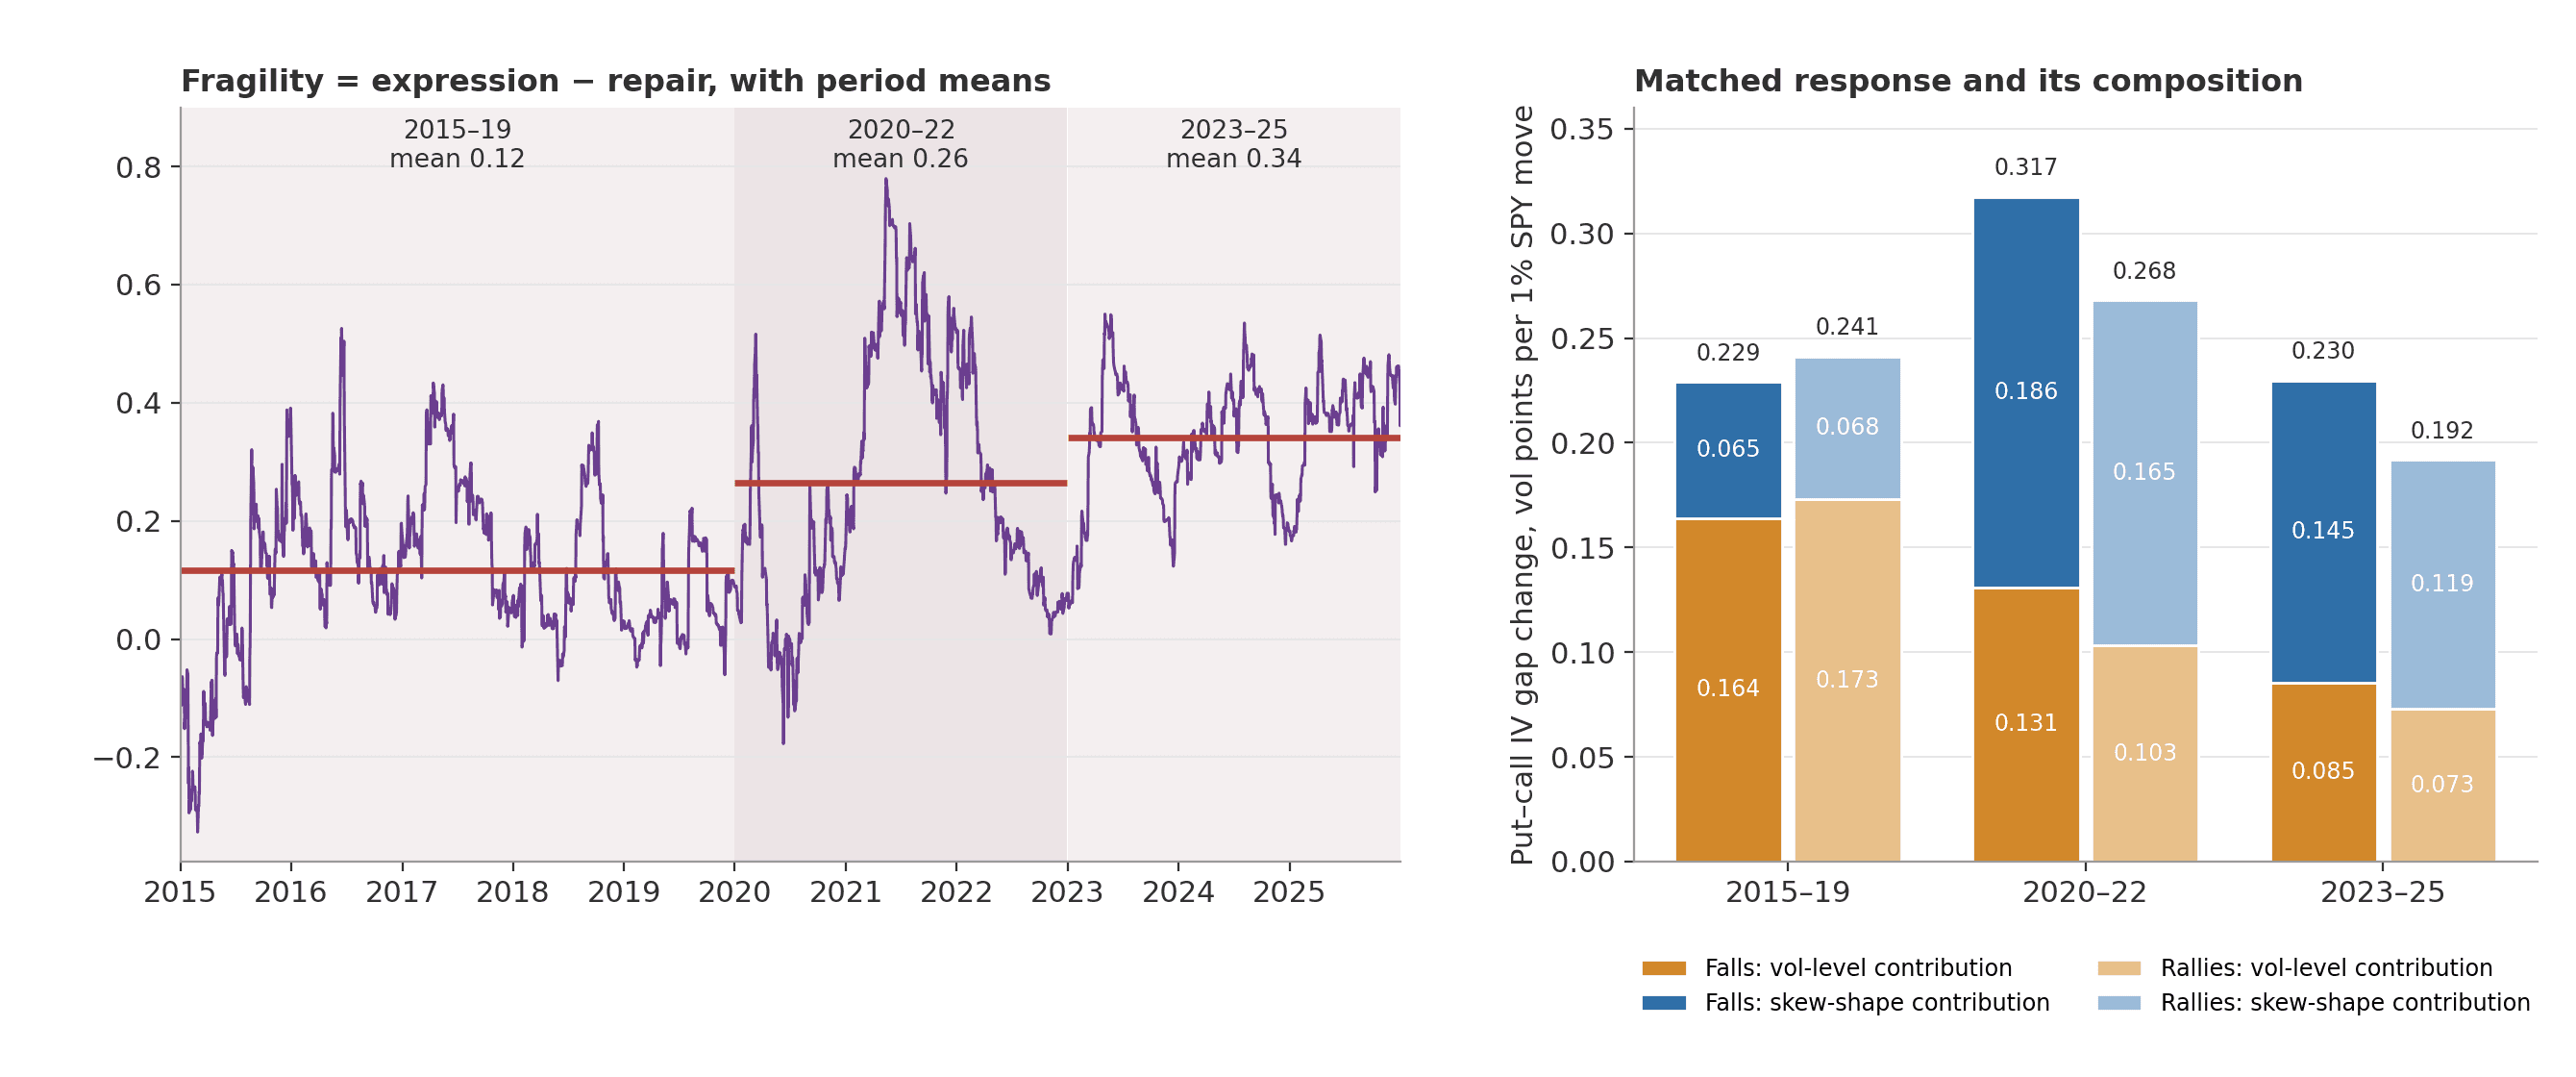
Left: fragility (expression minus repair), built from a log ratio that sees only the smile's tilt, with its mean over each period. Right: the put–call IV gap response per 1% SPY move by period, split into the vol-level and skew-shape parts that add to it, falls and rallies, total above each bar; 0.5–2% moves matched on direction, size and the basket's prior 30-day IV, 884 matched days.
Study · Volatility

More tilt, less level: how protection's response to falls has changed

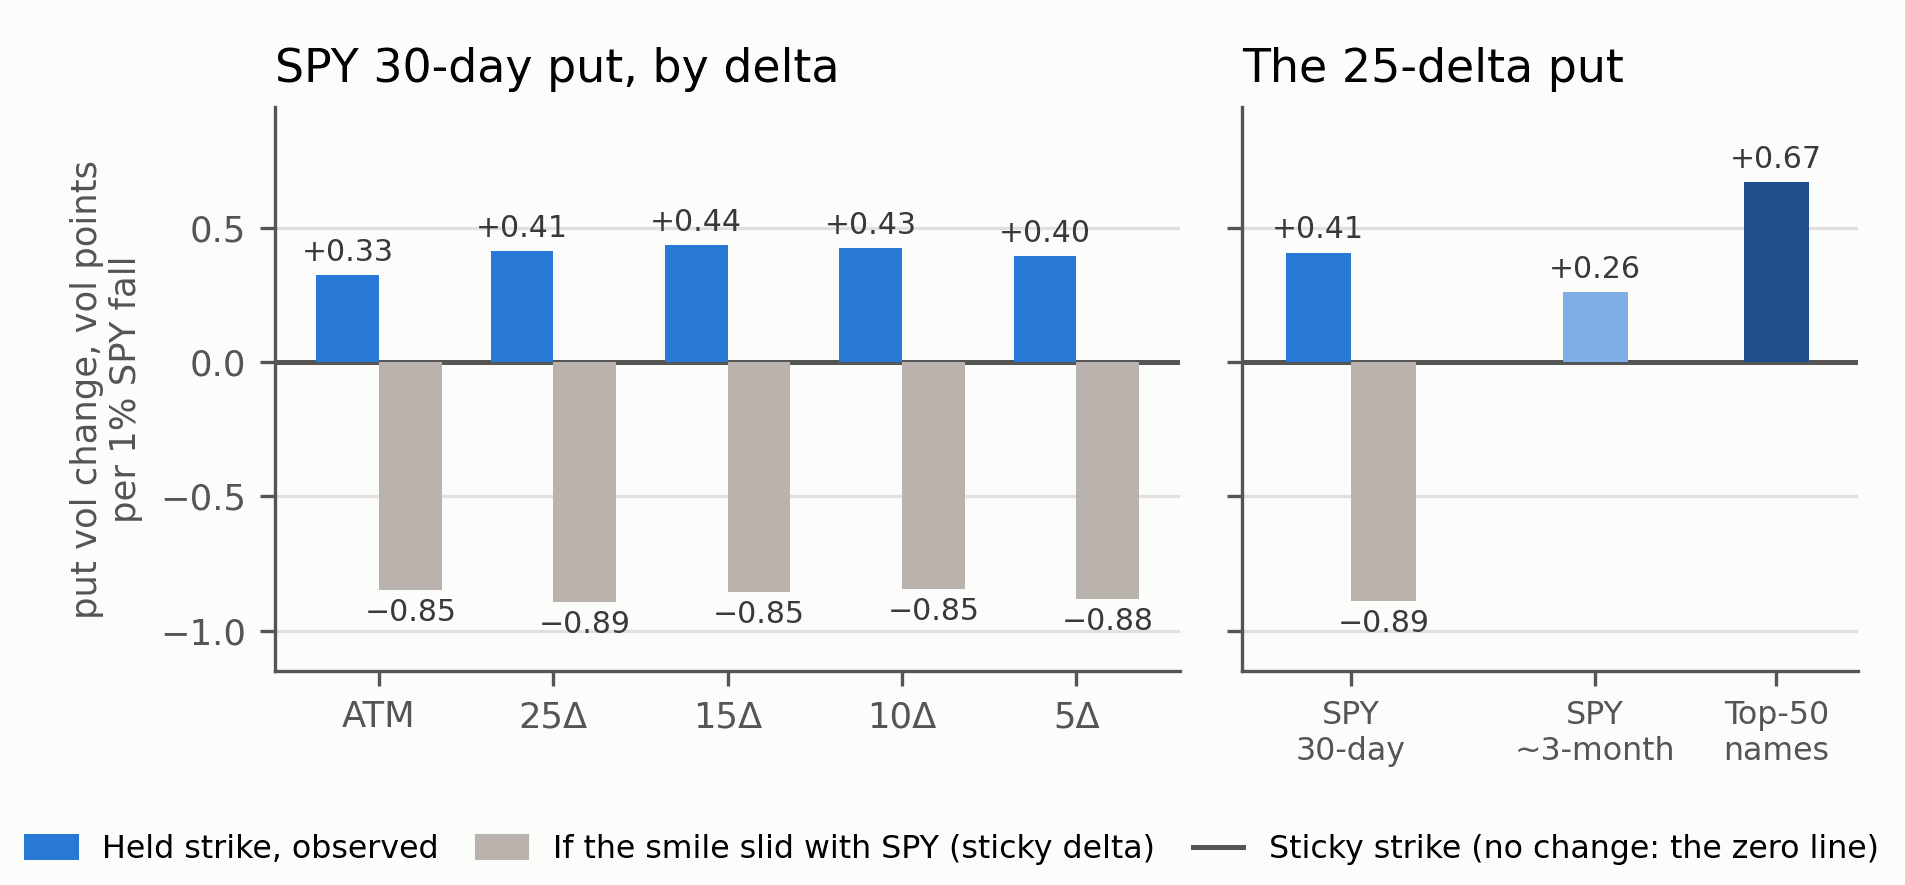
On ordinary 0.5–2% SPY falls, the constituents' skew now tilts more than it did before 2020 and their volatility level moves less, but the put–call gap a hedge is priced on changed far less than either part. At the strike a book holds, most of the surface move is slide, protection marks mostly on spot, and what fell is the cost of entry.

Read 13 min

How it works

Start with a conversation.

01Name an episode.

One where the decision to restore or reduce risk was difficult.

02We reconstruct it.

On our standard fifty names, dated to what was knowable each day, beside what your process showed. No holdings needed.

03Then an evaluation.

Ninety days, scoped together, the fee credited against a Terminal subscription: twelve screens, an API and an MCP server.

Institutional investors only. Diligence materials on request. Speak directly with Gunjeet, the founder, in Singapore or over a call.

Write to[email protected]